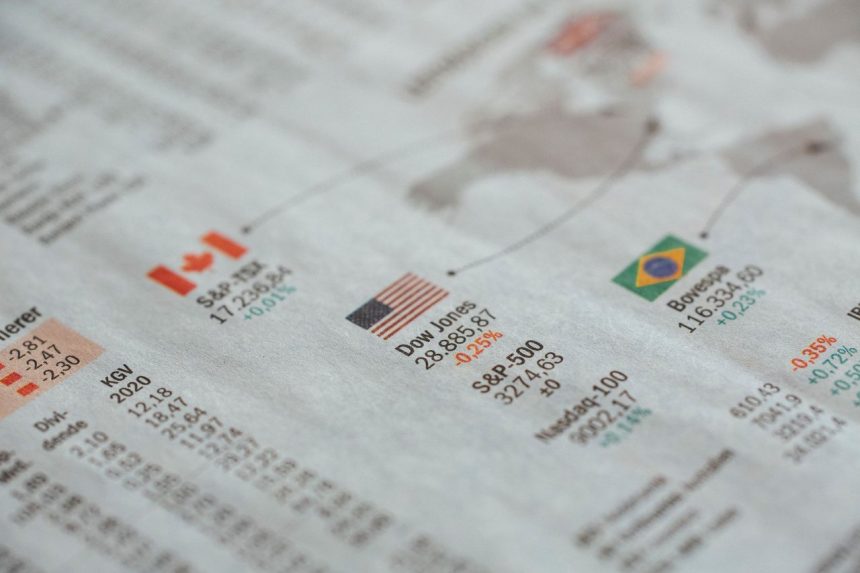
Changes in the cost of borrowing in the United States helped redirect investor attention across global markets on October 7, 2026, putting fresh pressure on Brazilian assets. The dollar closed at 5.016 reais, up 0.83%, while Brazil’s benchmark Ibovespa stock index fell 0.74% to 204,302.33 points.
The session reflected the combined effect of international financial conditions, higher oil prices and adjustments in Brazil after the first round of the country’s 2026 elections. The election-related movement was part of the domestic backdrop, but the main force highlighted in the market was external: the rise in yields on long-term U.S. government debt and the resulting reassessment of risk by investors.
According to Agência Brasil, the yield on 10-year U.S. Treasury bonds reached 5.36% during the day, its highest level in 24 years, before retreating. The movement increased caution in financial markets and coincided with the dollar’s return above the 5-real level in Brazil.
Why U.S. Treasury yields matter to Brazil
U.S. Treasury securities are closely followed by investors around the world because they are treated as a reference for dollar-denominated returns and as a relatively safer destination for capital. When their yields rise, the potential return available in the United States becomes more attractive compared with assets exposed to emerging-market risk.
That change can encourage a reallocation of funds toward U.S. assets and away from currencies and markets such as Brazil’s. In practical terms, stronger demand for dollars can weigh on the real, while local stocks may face additional pressure as investors become more selective. The effect does not depend on a decision made in Brazil alone: the change in global financing conditions can influence the value of the currency and the cost of raising money domestically.
The October 7 movement illustrates that connection. As Treasury yields climbed, investors reassessed the balance between risk and return across markets. The result was a stronger dollar in Brazil and a weaker Ibovespa at the end of the session, even though the Treasury yield later moved away from its intraday peak.
Oil above $100 adds another source of pressure
Oil prices also remained above $100 per barrel during the session, adding another important element to the international environment. Energy is a central component of the global economy, and higher prices can affect inflation expectations, trade flows and the outlook for interest rates in different countries.
For Brazil, the combination of expensive oil and a stronger dollar can complicate the economic outlook. A more valuable dollar raises the domestic-currency cost of imported goods and inputs, while higher energy prices can increase pressure throughout production and transportation chains. These effects can influence expectations about inflation and financing, although the available market report does not establish a separate measure for each of those impacts.
The simultaneous movement of oil prices and U.S. bond yields therefore matters beyond the financial market screens. It connects international energy costs, the dollar exchange rate and the performance of Brazilian investments in a single trading environment. For companies and consumers, exchange-rate volatility can make planning more difficult, particularly when global conditions remain unsettled.
A market adjustment rather than a conclusion
The dollar’s close at 5.016 reais does not, by itself, establish a lasting trend. The session was shaped by a specific combination of higher Treasury yields, oil above $100 and post-election adjustments in Brazil. The report also noted that the 10-year Treasury yield declined after reaching its intraday high, showing how quickly conditions can change during a trading day.
Even so, the episode demonstrates why Brazil’s markets remain sensitive to developments in the United States and other major financial centers. Decisions and expectations formed abroad can affect capital flows, the exchange rate and stock prices in São Paulo without any equivalent change occurring in the Brazilian economy on the same day.
For investors and businesses, the key issue is whether the international pressure persists. Continued high U.S. yields could keep emerging-market currencies under scrutiny, while oil prices above $100 could reinforce concerns about inflation and costs. If those conditions ease, part of the pressure may also diminish. The October 7 session, however, showed how quickly global borrowing costs can reach the Brazilian real and the Ibovespa.